


Cost Segregation for Vacation Rentals: What Property Owners Should Know in 2026
Owning a vacation rental is not only an investment in real estate. It is also an operating business with furnishings, appliances, outdoor improvements and building components that may have different tax lives.
Normally, the residential portion of a rental property is depreciated over 27.5 years. A cost-segregation study takes a closer look at the property and identifies components that may qualify for shorter depreciation periods—often five, seven or 15 years.
For some vacation-rental owners, this can produce significantly larger depreciation deductions during the early years of ownership. However, cost segregation does not create additional depreciation out of nowhere. It changes when eligible depreciation is recognized.
Here is what vacation-rental owners should understand before deciding whether a cost-segregation study belongs in their investment strategy.
Important: This article provides general educational information and is not tax, legal or financial advice. Tax treatment depends on the property, ownership structure, personal use, rental activity and the owner’s individual circumstances. Consult a qualified CPA or tax advisor before making a decision.
What Is Cost Segregation?
Cost segregation is a tax-planning strategy that separates the cost of an income-producing property into different asset classes.
Without a cost-segregation study, most of the building’s depreciable basis may be treated as residential rental property and depreciated over 27.5 years. The value allocated to land is not depreciable.
A cost-segregation study examines the building and its improvements in greater detail. Certain components may be reclassified into shorter recovery periods, such as:
- Five-year personal property
- Seven-year personal property
- Fifteen-year land improvements
- Twenty-seven-and-a-half-year residential rental property
This may accelerate a portion of the property’s depreciation into earlier tax years.
How Does Cost Segregation Work for a Vacation Rental?
A vacation rental contains more than the structure itself. Depending on the facts, potentially shorter-life components might include certain:
- Furniture and décor
- Appliances
- Carpeting and removable floor coverings
- Window treatments
- Specialty lighting
- Dedicated electrical components
- Cabinetry or millwork serving a specific function
- Fencing
- Patios and certain hardscaping
- Landscaping and irrigation
- Walkways
- Outdoor recreational improvements
Not every feature automatically qualifies for accelerated treatment. Classification depends on how the asset is attached, how it is used and the applicable tax rules.
A qualified cost-segregation professional studies the property’s purchase information, construction details, improvement history, plans, photographs and other records. The resulting report allocates eligible costs among the appropriate asset classifications.
Why Vacation Rentals Can Be Strong Candidates
Vacation rentals are often furnished and amenity-rich. A professionally operated home may include:
- Complete bedroom and living-room furnishings
- Multiple televisions and entertainment systems
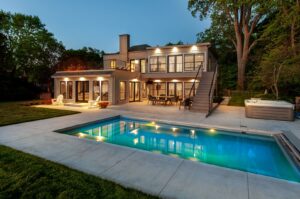
- Hot tubs or pools
- Game rooms
- Outdoor dining areas
- Fire pits
- Patios, walkways and landscaping
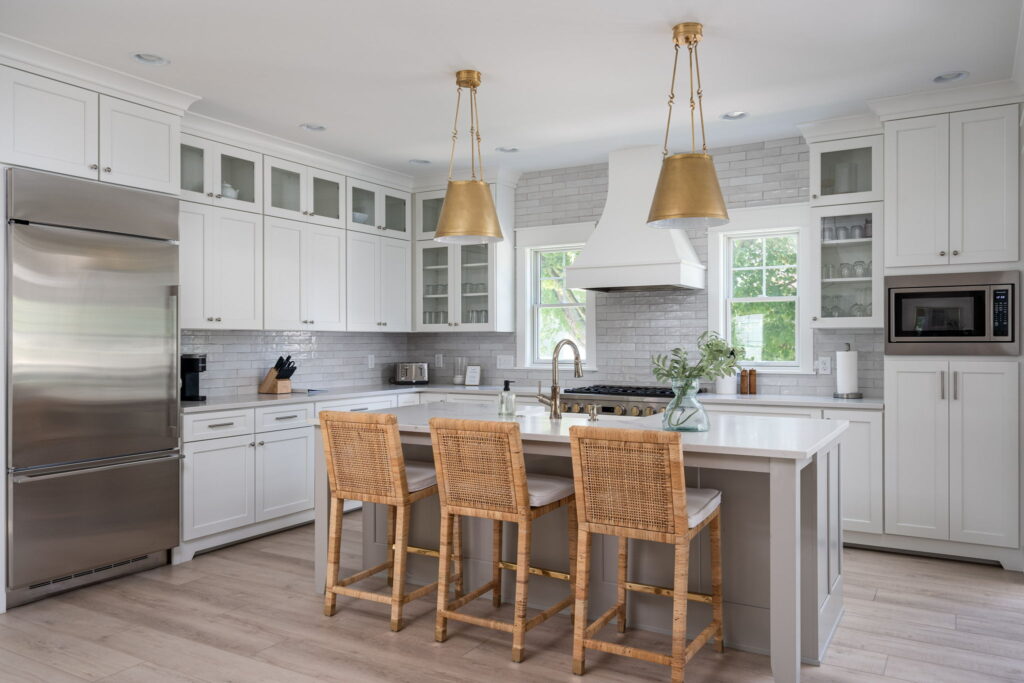
- Upgraded kitchens
- Guest-focused lighting and electrical improvements
Those features can make the property meaningfully different from an unfurnished long-term rental.
The more qualifying personal property and land improvements a vacation rental contains, the more potential there may be to accelerate depreciation. That does not mean every high-value or luxury home will receive the same result. The purchase price, land value, property design, improvements, documentation and ownership timeline all matter.
Cost Segregation and Bonus Depreciation in 2026
Cost segregation and bonus depreciation are related, but they are not the same strategy.
Cost segregation identifies which components belong in shorter asset classes. Bonus depreciation may then allow qualifying property to be deducted more quickly.
Federal legislation enacted in 2025 restored 100% bonus depreciation for qualifying property acquired after January 19, 2025, subject to the law’s requirements. This can make cost segregation especially valuable for some recent property acquisitions and improvements.
The main residential building generally does not become eligible for bonus depreciation simply because a study is performed. The potential benefit applies to components that are properly classified as qualifying shorter-life property.
Owners should confirm the following with a tax professional:
- When the property was acquired
- When it was placed in service
- Whether the assets meet the applicable qualification rules
- Whether any available election should be made
- How state tax treatment differs from federal treatment
Michigan, Florida and an owner’s state of residence may not treat every deduction in exactly the same way.
A Simplified Cost-Segregation Example
Consider an investor who purchases a furnished vacation rental for $1.2 million.
After subtracting the value allocated to land, assume the property has a depreciable basis of $950,000. Without cost segregation, much of that basis might be depreciated over 27.5 years.
A detailed study might determine that a portion of the basis belongs to qualifying five-, seven- or 15-year assets. Depending on the placed-in-service date and the owner’s circumstances, some shorter-life assets may also qualify for bonus depreciation.
This could create a considerably larger first-year depreciation deduction than the owner would receive under the standard schedule.
However, a larger depreciation deduction is not the same as a dollar-for-dollar tax refund. The actual effect depends on factors such as:
- The owner’s taxable income
- Marginal tax rate
- Passive-activity rules
- Material participation
- At-risk limitations
- Personal use of the home
- The property’s placed-in-service date
- State tax rules
- Future sale plans
The study accelerates eligible deductions. Whether the owner can use those deductions immediately is a separate question.
Can Cost Segregation Offset an Owner’s Other Income?
Sometimes—but not automatically.
Rental activities are generally subject to passive-activity rules. A tax loss from a vacation rental may be limited, suspended or available only against certain income.
Short-term rentals can receive different tax treatment from traditional long-term rentals in some circumstances, particularly when the average guest stay and the owner’s level of participation meet specific tests. Providing substantial guest services may introduce additional considerations.
This is one of the most important areas to discuss with a CPA who understands short-term rentals. A cost-segregation study may produce a substantial deduction on paper, but its immediate value depends on whether the owner is permitted to use the resulting loss.
Does Personal Use Affect the Tax Benefit?
Yes. Many vacation-rental owners also reserve time for themselves, their families or friends.
The IRS applies special rules when a dwelling is used both personally and as a rental. A property may be treated as a residence for tax purposes if personal use exceeds the greater of:
- 14 days, or
- 10% of the days the home is rented at a fair rental price
Personal use can affect the allocation and deductibility of rental expenses. Days provided to friends or family for less than fair rental value may also be treated as personal-use days.
Owners should keep accurate records of:
- Rental days
- Personal-use days
- Maintenance days
- Dates the property was available but unoccupied
- Amounts charged for each stay
- Property-related expenditures
Good operational records support good tax records.
Can an Owner Complete a Cost-Segregation Study Later?
Potentially. Cost segregation is not necessarily limited to the year a property is purchased.
An owner who placed a rental property into service during a previous year may be able to perform a “look-back” study. In some circumstances, the owner can claim missed depreciation through an accounting-method adjustment rather than amending every prior return.
This process is more complex than completing a study when a property is first placed in service. A tax professional should determine whether a look-back study is appropriate and whether additional forms or procedural steps are required.
What Does a Quality Cost-Segregation Study Include?
A reliable study should be based on more than a generic percentage applied to the purchase price.
Depending on the property, a thorough report may include:
- Property and ownership details
- Acquisition and placed-in-service dates
- Land and building-value allocation
- Review of closing and construction documents
- Examination of renovation costs
- Property photographs or an on-site inspection
- Identification of individual building components
- Applicable asset classifications
- Depreciation schedules
- Explanation of the study methodology
- Support for the tax positions used
The IRS publishes a Cost Segregation Audit Technique Guide that discusses study methodologies and documentation. Although the guide is written for IRS examiners, it helps demonstrate why the quality and support behind a study matter.
Owners should look for providers with relevant engineering, construction and tax expertise—and ensure their CPA is prepared to review and use the final report.

What Are the Potential Drawbacks?
Cost segregation can be valuable, but it is not automatically the right answer for every owner.
Considerations include:
Study cost
A formal study has an upfront cost. The anticipated tax benefit should justify that expense.
Depreciation recapture
Accelerated depreciation can affect taxes when the property or individual assets are sold. Owners should discuss depreciation recapture and their expected holding period with their advisors.
Passive-loss limitations
A deduction may be generated without being immediately usable.
State-tax differences
A state may not fully conform to federal bonus-depreciation rules.
Personal-use limitations
Mixed personal and rental use can change the tax treatment.
Documentation requirements
An aggressive or poorly supported study may increase audit risk. The goal should be a defensible allocation—not the largest number a provider is willing to advertise.
Questions to Ask Before Ordering a Study
Before moving forward, vacation-rental owners should ask:
- Is my property’s depreciable basis large enough to justify the study?
- How much of the property might reasonably qualify for shorter recovery periods?
- Can I currently use the additional depreciation?
- How will my personal use of the property affect the deduction?
- Does the placed-in-service date qualify the assets for bonus depreciation?
- How will my state treat the deduction?
- How long do I expect to own the property?
- What might depreciation recapture look like when I sell?
- Does the study provider have experience with vacation rentals?
- Will my CPA review the methodology before the return is filed?
Cost Segregation Is One Part of a Larger Investment Strategy
Tax efficiency matters, but it cannot replace strong property performance.
A vacation rental still needs:
- Appropriate nightly-rate and revenue management
- Professional presentation and photography
- Broad but strategic distribution
- Consistent guest communication
- Reliable local operations
- Preventive property care
- Accurate performance reporting
- Marketing that reaches the right travelers
Accelerated depreciation may improve near-term cash flow for a qualifying owner. Professional vacation-rental management helps address the revenue, guest experience and long-term asset performance behind that investment.
Beachwalk Properties works with vacation-rental homeowners to position, market and manage distinctive homes across our growing service areas. If you are evaluating the performance of an existing rental—or considering bringing a new property to market—our team would be happy to discuss the operational and marketing side of your investment.
Frequently Asked Questions
What is cost segregation for a vacation rental?
Cost segregation is a tax-planning method that identifies components of a vacation-rental property that may qualify for shorter depreciation periods than the residential building itself. This can accelerate eligible depreciation deductions.
Is cost segregation only for commercial buildings?
No. Residential rental properties, including qualifying vacation rentals, may also be candidates for cost segregation.
Is the land included in a cost-segregation study?
Land is not depreciable. A study may analyze qualifying land improvements, but the underlying value of the land must be separated from the property’s depreciable basis.
Can furniture in a vacation rental be depreciated?
Furniture used in an income-producing vacation rental is generally depreciable business property. The specific recovery period and eligibility for bonus depreciation should be confirmed with a tax professional.
Does a cost-segregation study guarantee tax savings?
No. The study may accelerate depreciation, but the owner’s ability to use the deduction depends on income, participation, personal use, passive-loss rules, state law and other tax circumstances.
Can I use cost segregation on a vacation rental I already own?
Possibly. A look-back study may allow an owner to identify depreciation that was not claimed in prior years, subject to applicable accounting-method and filing requirements.
What happens when I sell the property?
Previously claimed depreciation can affect taxable gain and depreciation recapture. Owners should consider their anticipated holding period and exit strategy before accelerating deductions.
Who should perform a cost-segregation study?
Owners should seek a qualified provider with appropriate tax, engineering or construction expertise and experience supporting its classification methodology. The owner’s CPA or tax advisor should review the study.